
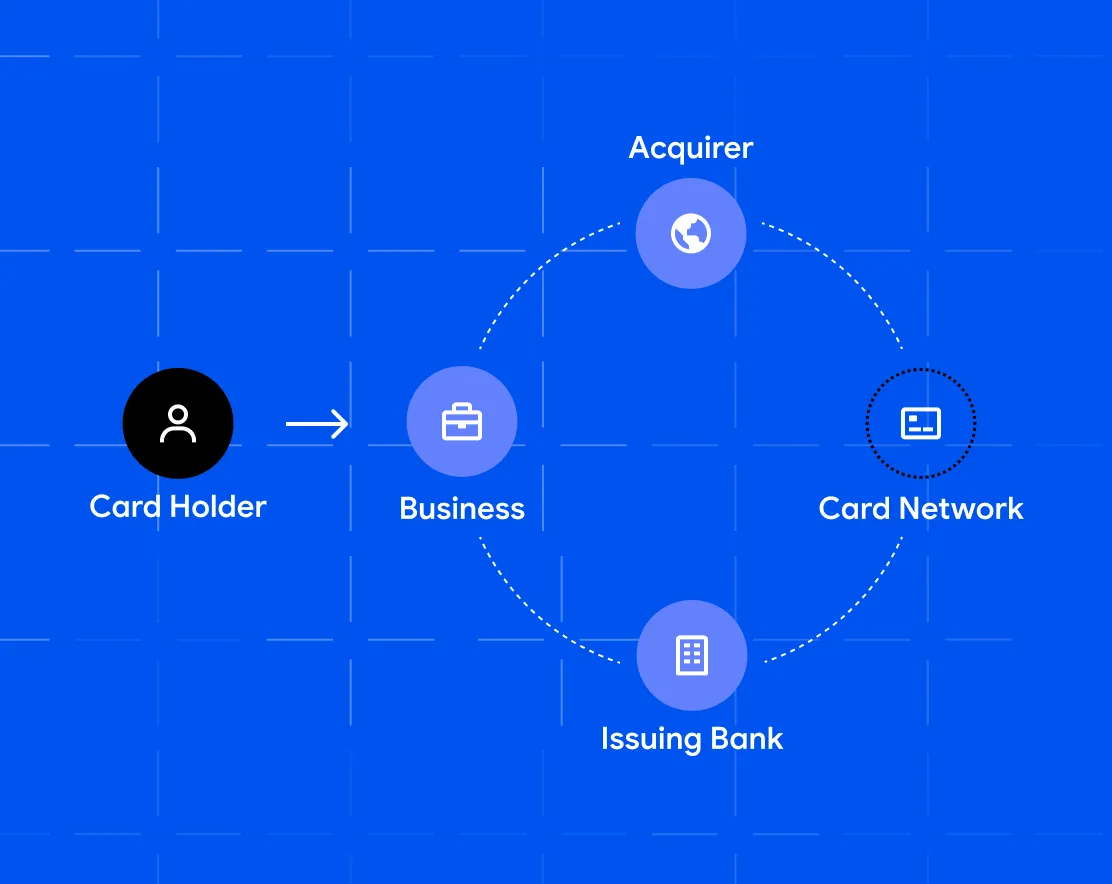


Payment processing is the sequence of steps that moves money from a customer's card or account to a merchant's bank account. It happens in three stages: authorization, authentication and settlement. A payment processor handles the communication between the banks and card networks at every stage.
If you run a business, it helps to understand the basics. You want payments to arrive smoothly, but that's not all. As soon as customers enter their payment details on your site, you're responsible for their financial information, so it pays to know the process in case issues come up.
This guide explains what happens behind the scenes when a customer makes a purchase, and the best ways to accept payments on your website.
What is payment processing and why do you need it?
Payment processing describes the steps that happen behind the scenes of an electronic transaction, whether it's made by credit card, debit card, digital wallet or another digital payment method.
If you sell goods, services or subscriptions on your own website, you need a way to accept credit cards and other payment methods, and the infrastructure to keep transactions smooth and secure.
Accepting online payments carries risk. Cards can be stolen or counterfeit, and cybercriminals look for merchants they can take advantage of.
A payment processor takes care of this for you. When someone pays by card, the processor verifies the card and handles all communication between the banks and card companies involved.
How does payment processing work?
Payment processing happens in three steps: authorization, authentication and settlement.

Step 1: Authorization
For a card payment to succeed, the card details must be verified and authorized. This confirms the card is valid and legitimate:
- The customer enters their card details on a checkout page or inserts their card into a POS terminal in a physical store.
- The card details are encrypted and sent to the acquiring bank (the seller's bank).
- The acquiring bank sends the details to the card network (for example, Visa, Mastercard or American Express).
- The card network passes the request to the issuing bank (the customer's bank) to authorize the transaction.
- The issuing bank authorizes it after checking the card number, expiry date, security code, billing address and amount.
The payment processor handles all of this communication. It sounds like a lot of steps, but it usually takes only a few moments.
Step 2: Authentication
Once the issuing bank has verified the card, it authenticates the purchase so the payment can be released to the acquiring bank:
- The issuing bank sends its approval to the card network.
- The card network passes the authorization to the acquiring bank.
- The issuing bank places a temporary hold on the customer's account for the purchase amount. When the transaction clears, these funds are withdrawn and deposited in the seller's account.
- The customer sees a confirmation on the checkout page, or gets a printed receipt in a physical store.
If the issuing bank doesn't approve the transaction, it notifies the card network and acquiring bank, and the transaction is cancelled. The customer sees an error message, usually explaining why.
Step 3: Settlement
In the final stage, the issuing bank releases the funds and they're transferred to the seller's account at the acquiring bank. It can take a few days before the seller sees the money:
- At the end of each day, all approved authorizations are sent to the acquiring bank.
- The acquiring bank passes them to the card network.
- The card network settles each transaction: getting funds to the seller, removing the hold on the customer's account and finalising the transaction.
- The card network notifies the issuing bank of all approved transactions.
- The issuing bank transfers the funds to the card network.
- The card network passes the funds to the acquiring bank.
- The acquiring bank deposits the funds in the seller's account.
- The issuing bank deducts the funds from the customer's account and closes the transaction.
How to optimize your payment system to grow revenue
The best businesses are always looking for ways to grow revenue. Here are four ways to optimize your payment system for more sales.
Speed up checkout
Online shoppers expect checkout to take under 10 seconds. With digital wallets capturing 53% of global online purchases, speed is essential.
With Pay.com, you can securely store customers' details and payment preferences, so returning customers don't have to re-enter everything. That speeds up payment, reduces cart abandonment and increases conversion rates.
Make checkout mobile-friendly
Mobile commerce keeps growing worldwide, and billions of consumers use digital wallets on their phones. Make sure your checkout works smoothly on small screens, and accept mobile-friendly methods like Google Pay and Apple Pay.
Put an emphasis on security
As cybercrime rises, shoppers need to feel safe paying online. A lack of visible security is one of the leading causes of cart abandonment.
Pay.com uses the 3D Secure protocol for an extra layer of security. Show the 3D Secure symbol and other security logos throughout checkout to build trust.
Offer a range of payment options
Offering local payment options builds trust and increases sales. Digital wallets now reach over 60% of the global population, with 5.2 billion users.
Beyond wallets, BNPL (buy now, pay later) services have grown to $28.44 billion in annual revenue, and A2A (account-to-account) payments reached $1.4 trillion in consumer transactions in 2026.
Pay.com lets you accept a wide range of payment methods on your website, from traditional cards to the latest digital options.
Payment processing terminology
Key terms every business owner should know:
- Credit card processing: the system that sends card data through an electronic card network, validates and approves transactions, and moves funds between accounts.
- Debit card processing: similar to credit card processing but simpler, and usually on different networks. You can typically accept both with the same software (and hardware, if needed).
- ACH transfers: the Automated Clearing House (ACH) network, run by NACHA, routes payments between banks. It's used for money transfers, recurring payments, paycheck deposits and more.
- Mobile payment systems: also called mobile or digital wallets, these let users pay on their mobile devices without entering card details each time. Examples include Google Pay and Apple Pay.
- Payment processor: a company that lets merchants accept payments and processes those payments for them.
- Payment gateway: the online version of a POS terminal. Payment gateways capture card data, send it to the processor and communicate approvals or rejections.
- POS (point of sale) terminal: hardware and software that let physical stores accept card payments, usually a computer plus card readers and receipt printers.
- Merchant bank (acquirer): the financial institution a merchant uses to accept card payments.
- Card issuer: the financial institution that issues credit and debit cards on behalf of networks like Visa, Mastercard and American Express.
- Card network: the company that connects merchant banks and card issuers. The four main networks are Visa, Mastercard, Discover and American Express.
- Address Verification System (AVS): a card network service that checks whether the billing address a customer enters matches the one the issuer has on file. It helps reduce fraud and chargebacks.
How to protect yourself from fraud
Billions of dollars are processed every day. Most transactions run smoothly, but fraud is the biggest risk and can cost you a lot of money. These steps help reduce it:
- Choose a PCI-compliant processor. You don't need to be a security expert, but your processor should use the latest protections. Pay.com offers PCI-compliant data security and protection.
- Ask for more card details. Require the billing address, expiry date and CVV code. The more data you collect, the harder fraud becomes.
- Use SSL and 3DS2. SSL certificates and measures like 3DS2 protect every transaction in your store. Most processors require SSL for ecommerce merchants.
- Keep everything updated. Install the latest patches and security updates on all your hardware and software.
The bottom line: how to choose a payment processor
Research carefully to find the best processor for your business. Make sure it lets you accept a variety of payment methods, not just credit and debit cards.
Security is critical for online transactions, so always choose a PCI-compliant processor, and ask what fraud prevention it has in place.
Pay.com provides a complete payment infrastructure for accepting payments on your website. It's easy to set up, even if you're selling online for the first time, and comes with the latest security and fraud protection.
FAQs
How long does it take to process a payment?
Processing itself takes seconds or a few minutes at most. Settlement, when the seller actually receives the funds, can take 3–5 business days depending on the payment method.
Does processed mean paid?
Not necessarily. A processed transaction may be authorized and authenticated but not yet settled, so the seller may not see the funds yet.
How secure is payment processing?
Any card payment carries some risk of identity theft or fraud: the card could be stolen, or data could be intercepted during processing. Payment processors use many protections to prevent this. With a secure payment infrastructure like Pay.com, all data is encrypted and sent through secure channels.
Why are card transactions denied?
Often it's just a typo in the card details. Other reasons include the processor not accepting that card type, insufficient funds, extra verification being needed, or a technical error during payment.
How do I decide which payment processor to use?
Once you know what you need, focus on flexibility, ease of use, the range of payment methods supported, and security features.
Will my business qualify for a merchant account?
It depends. Past bankruptcies or a poor credit report can make approval harder. If your credit history has no major problems and you can provide the required information, you should be able to open a merchant account.
How much does payment processing cost?
Card processing fees usually cost between 1.5% and 3.5% of each transaction. Choose a payment services provider that is fully transparent about its fees.
Pay.com lets you accept a variety of payment methods on your website and provides a full payment infrastructure to cover all your needs. It’s easy to set up and you don’t need any technical experience.

Emily is a content writer with a special interest in fintech and business. She loves sharing her knowledge to help small businesses take their first steps towards success.
Read next
Get payments insights in your inbox


