
What’s a Chargeback? How Can It Affect Your Business? [2026]
10 min read
•
17 Apr 2026
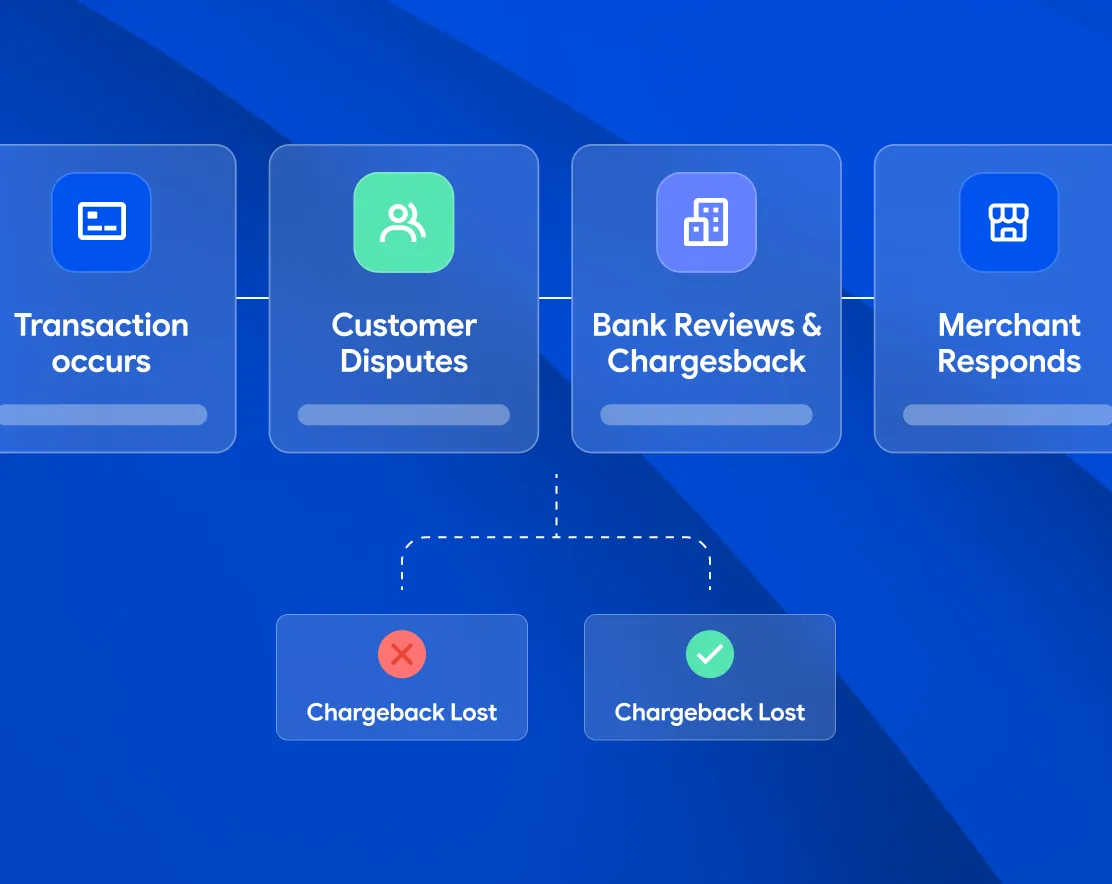


A chargeback is a forced reversal of a card payment, started by the cardholder's bank after the cardholder disputes a transaction. For merchants, chargebacks mean lost revenue, extra fees and, if they pile up, the risk of losing the ability to accept card payments.
Chargebacks are an unfortunate but necessary part of doing business online. They hold merchants to a high standard and protect consumers from fraudulent charges. But they also come at a real cost: lost merchandise, lower profits and, in the worst case, a merchant account that gets shut down.
At Pay.com, we know chargebacks can be confusing because so many factors are involved. This guide covers what chargebacks are, why they happen and how they work, so you can take the right steps to prevent and dispute them.
What is a chargeback?
A chargeback is initiated by a cardholder to dispute a debit or credit card payment they believe is illegitimate. When it happens, the card issuer forces a reimbursement of the transaction.
Chargebacks can happen at any time after a sale, but they are most common within the first 120 days.
How does a chargeback work?
The chargeback process is set and managed by the card networks, and financial institutions and merchants must follow it. The parties involved are:
- The cardholder
- The issuing bank
- The acquiring bank
- The card network
- The merchant
The process differs slightly between card networks, but it generally looks like this:
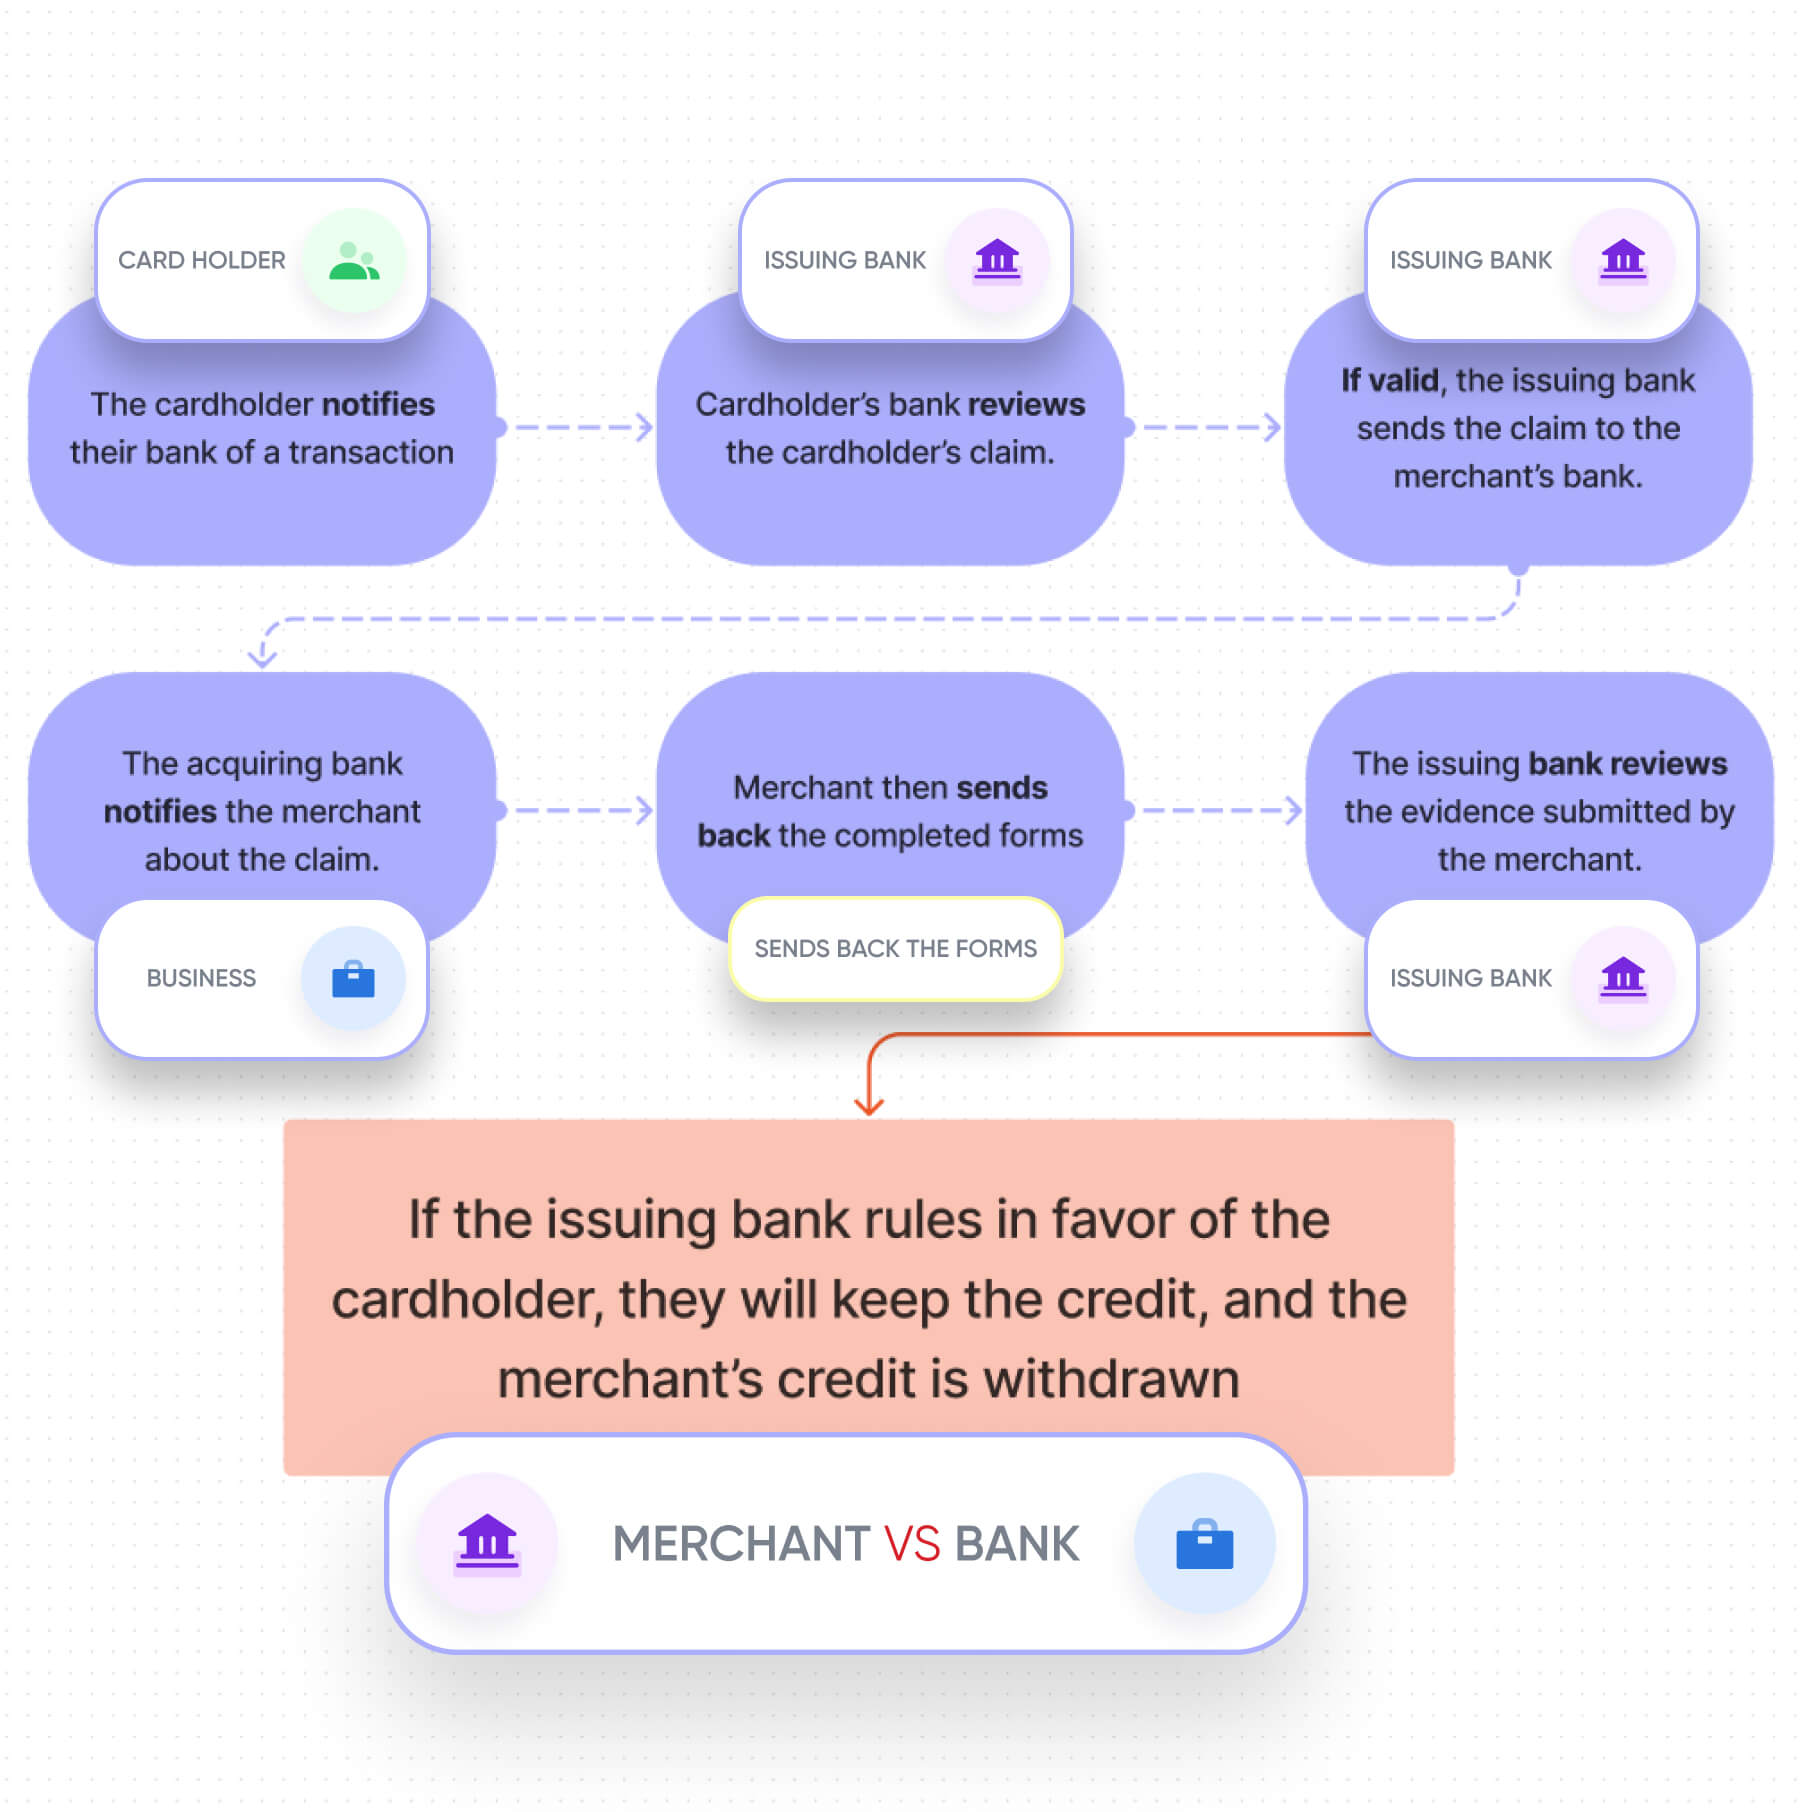
- The cardholder contacts their bank about a transaction they want to dispute.
- The cardholder's bank reviews the claim.
- If the claim is valid, the issuing bank sends it to the merchant's bank.
- The acquiring bank notifies the merchant. It also tells the merchant that the transaction amount has been debited from their account to reimburse the cardholder.
- If the merchant wants to fight the chargeback, they get forms to fill out and return within 7–10 days explaining their side of the dispute.
- The merchant returns the completed forms to the acquiring bank. The acquirer passes them to the cardholder's bank and gives the merchant a provisional credit for the chargeback amount.
- The issuing bank reviews the merchant's evidence. If the merchant fulfilled the transaction correctly, they keep the credit and the cardholder's credit is withdrawn. If the bank rules for the cardholder, the cardholder keeps the credit and the merchant's credit is withdrawn.
What causes chargebacks?
Customers dispute card transactions for many reasons, and not all of them are legitimate. The most common are:
- The cardholder was the victim of a fraudulent transaction.
- The cardholder was overcharged for a product or service (a billing error).
- The merchant failed to deliver the goods or services.
- The merchant misrepresented a product or service.
- The cardholder is not satisfied with a product or service.
- The cardholder was charged after cancelling a subscription, or forgot to cancel one.
- The cardholder was accidentally charged twice for one purchase.
- The cardholder disputes a transaction for an illegitimate reason to keep goods or services without paying, also known as friendly fraud.
Chargeback vs. payment dispute: what's the difference?
The two terms are often used interchangeably, but they refer to different things.
A payment dispute happens when a cardholder challenges a transaction on their statement. Most disputes start when a customer sees a charge they don't think they made. Other common causes are incorrect amounts and goods or services that never arrived.
A chargeback is the forced reimbursement the card issuer initiates. In other words, the dispute is the process the cardholder starts, and a chargeback is one possible result of it. Not every dispute ends in a chargeback.
Chargeback fees
A chargeback or dispute fee is charged by the acquiring bank to cover the cost of processing the chargeback. When the cardholder's bank processes a chargeback or dispute, you as the merchant will very likely be charged this fee.
The amount depends on the bank but usually ranges from $10 to $50. High-risk merchants can pay much more.
There are also hidden costs many merchants don't think about:
- Processing fees are not returned when a chargeback occurs, so you absorb that cost.
- Operational costs that went into the order, such as warehousing, logistics and shipping, are lost too.
The good news is that you can lower your risk. Confirm the cardholder's identity, make your billing terms clear, and put your shipping and return policies somewhere easy to find on your website.
How to handle chargebacks (step by step)
Chargebacks are bound to happen regularly, so be ready to respond. The most important habit is staying organised and keeping good records. Then, when a customer disputes a charge, you can fill out the required forms and respond as soon as you're notified.
Without good records, or the authentication details collected at the time of purchase, handling chargebacks becomes slow and cumbersome.
It's also essential to know why the chargeback happened. The issuing bank attaches a reason code to the transaction, and that code tells you what the dispute is about.
You can't afford to simply accept every chargeback. To defend valid transactions and recover lost revenue, use the chargeback representment process: the regulated process for responding to unwarranted chargebacks.
To fight a chargeback successfully, you'll need to:
- Collect compelling evidence that fits the reason code and the card scheme's requirements, such as a sales receipt, customer messages and delivery confirmation.
- Write a chargeback rebuttal letter that summarises the evidence and explains why the transaction is valid.
- Submit the representment within the required deadline.
You can do all of this in-house if you have the resources and expertise. If not, consider a third party that specialises in chargebacks. Every merchant should also use a payment processor that offers chargeback protection.
How do other merchants handle it? According to the 2021 Payment Risk Mitigation Survey by Worldpay and Forrester Consulting, half of the merchants surveyed manage chargebacks in-house and 31% use external teams. Another 18% use a hybrid of internal teams and third-party providers.
How does a chargeback work on a credit card?
Credit card chargebacks are a strong protection for cardholders and are often successful. The process is now so easy that more merchants report customers using chargebacks instead of asking for refunds. 80% of merchants surveyed also reported an increase in friendly fraud over the past three years.
Chargebacks no longer take a long time to process. Strict deadlines now set how long consumers, banks and merchants have to start or respond to a chargeback, and these deadlines vary by card network.
Visa chargeback deadlines
- Cardholders have 120 days from the day after the transaction date to file a chargeback for most issues.
- Merchants have 30 days to respond and fight a chargeback.
- Merchants have 10 days to file for arbitration.
Mastercard chargeback deadlines
- Cardholders have 120 days from the day of the transaction to file a chargeback for most issues.
- Merchants have 45 days to respond and fight a chargeback.
- Merchants have 45 days to file for arbitration.
American Express chargeback deadlines
- Cardholders have 120 days from the day of the transaction to file a chargeback for most issues.
- Merchants have 20 days to respond and fight a chargeback.
Merchant rights in the chargeback process
Consumers have a powerful tool in chargebacks, but merchants are not defenceless. You can dispute a chargeback whenever you see fit. Fighting one takes time and resources, but it is a right every merchant should use to recover lost revenue and protect against dishonest customers.
Other rights every merchant should know:
- The total of all chargebacks on a transaction cannot exceed the original purchase amount.
- If a customer files a chargeback for late delivery, they must first try to return the item. A chargeback is only possible if both the return and the refund are denied.
- Returned items are not eligible for a chargeback until 15 days after the return is received, giving merchants time to issue a refund.
Debit card chargebacks
Debit and credit card chargebacks differ in a few important ways. The biggest is that a debit card transaction takes money straight from the cardholder's bank account, while a credit card payment records a debt.
Refund times differ too. Debit card refunds usually take around 10 days, compared with 1–2 days for credit cards.
If a debit card dispute does turn into a chargeback, you follow the same steps to fight it as you would for a credit card chargeback.
The best way to prevent debit card chargebacks is to be proactive and communicate clearly. Make it easy for customers to contact you, and share your return, exchange and authorisation policies with them.
Visa chargeback process and reason codes
How the Visa dispute process works
When a Visa cardholder files a dispute, the transaction becomes a Visa dispute (a chargeback) and follows Visa's rules:
- The issuing bank credits the cardholder's account and notifies the merchant's acquiring bank.
- The acquirer notifies the merchant and debits their account for the transaction amount, plus any chargeback fees.
- If the merchant wants to fight the claim, they send evidence to the issuing bank showing the chargeback is illegitimate. If the evidence is accepted, the chargeback is reversed.
Visa chargeback reason codes
Every chargeback gets a reason code that tells the merchant why it was filed. Visa's codes fall into four categories:
- 10 – Fraud: no EMV chip was used, stolen card credentials were used, or the Visa Fraud Program flagged the transaction.
- 11 – Authorisation: the transaction lacked proper authorisation, or a Card Recovery Bulletin was ignored.
- 12 – Processing errors: incorrect transaction codes or account numbers, duplicate payments and similar issues.
- 13 – Customer disputes: services not received, products not as described, or defective or counterfeit goods, among other reasons.
Mastercard chargeback process and reason codes
How the Mastercard dispute process works
When a Mastercard holder files a dispute, the process follows Mastercard's own rules, which differ from Visa's:
- First presentment: the transaction amount is taken from the cardholder and credited to the merchant. If the cardholder disputes it, the issuing bank may ask the merchant for more information.
- Chargeback: the issuer starts a chargeback if the merchant doesn't respond or can't provide compelling evidence. If the merchant doesn't fight it, the full amount is withdrawn from the merchant's account and credited to the cardholder.
- Second presentment: if the merchant fights the chargeback, they send evidence to the acquirer. The acquirer can process a second presentment if the chargeback didn't meet the reason code's requirements and the evidence addresses the original reason for the dispute.
- Pre-arbitration (formerly arbitration chargeback): if the issuer isn't convinced, the case moves to pre-arbitration. The merchant can accept the chargeback or keep fighting with new evidence. The issuer then reverses the chargeback or moves to an arbitration case.
- Arbitration case filing: if the issuer and acquirer can't resolve the case, Mastercard steps in and decides who is responsible.
Mastercard chargeback reason codes
| Code | Description |
|---|---|
| 4837 | No Cardholder Authorization |
| 4840 | Fraudulent Processing of Transactions |
| 4849 | Questionable Merchant Activity |
| 4863 | Cardholders Does Not Recognize—Potential Fraud |
| 4870 | Chip Liability Shift |
| 4871 | Chip/PIN Liability Shift |
| 4807 | Warning Bulletin Files |
| 4808 | Authorization-Related Chargeback |
| 4812 | Account Number Not On File |
| 4834 | Point-of-Interaction Error |
| 4831 | Transaction Amount Differs |
| 4842 | Late Presentments |
| 4846 | Correct Transaction Currency Code Not Provided |
| 4850 | Installment Billing Dispute |
| 4999 | Domestic Chargeback Dispute (Europe Region Only) None Point-of-Interaction Error |
| 4853 | Cardholder Dispute |
| 4841 | Canceled Recurring or Digital Goods Transactions |
| 4854 | Cardholder Dispute—Not Elsewhere Classified (U.S. Region Only) |
| 4855 | Goods or Services Not Provided |
| 4859 | Addendum, No-show, or ATM Dispute |
| 4860 | Credit Not Processed |
How can Pay.com help reduce chargeback disputes?
Pay.com helps merchants increase conversions with a secure, fraud-resistant checkout that prevents certain fraud chargebacks and keeps your business in line with the latest PSD2 rules.
With our 3D Secure component, the system decides how risky each transaction is based on the amount and whether the shopper is known to your store. Regular customers spending an expected amount are exempted from extra checks. Only unfamiliar customers, large amounts and suspicious behaviour get stricter checks.
To find out how Pay.com protects you from fraud-based chargebacks, sign up now.
Learn more about our revenue optimization tools and the payment methods available for your eCommerce business, or start to accept online payments today.
Related content
Read next
Get payments insights in your inbox


